Like-for-like grocery inflation rose to 2.5%, compared to the 2.3% reported four weeks ago.
Commenting on the latest figures, Fraser McKevitt, head of retail and consumer insight at Worldpanel by Numerator, commented: “With the Autumn Budget fast approaching, the cost of living continues to weigh heavily on the minds of shoppers. And the cost of filling up a car is only adding to the pressure on household budgets.
“More than half tell us they’re very or extremely worried about petrol prices, and almost one in three say it’s already taking a real toll on their finances. Until the Chancellor sets out his plans, we expect that caution to carry on showing up at the till, with shoppers leaning more heavily on promotions to keep their grocery spend under control.”
With spending on promotions in the last month up by more than a quarter of a billion pounds compared with last year, Numerator said special offers remained a “key tool” for shoppers looking to keep their grocery bills in check, or to make pricier items and larger packs more affordable.
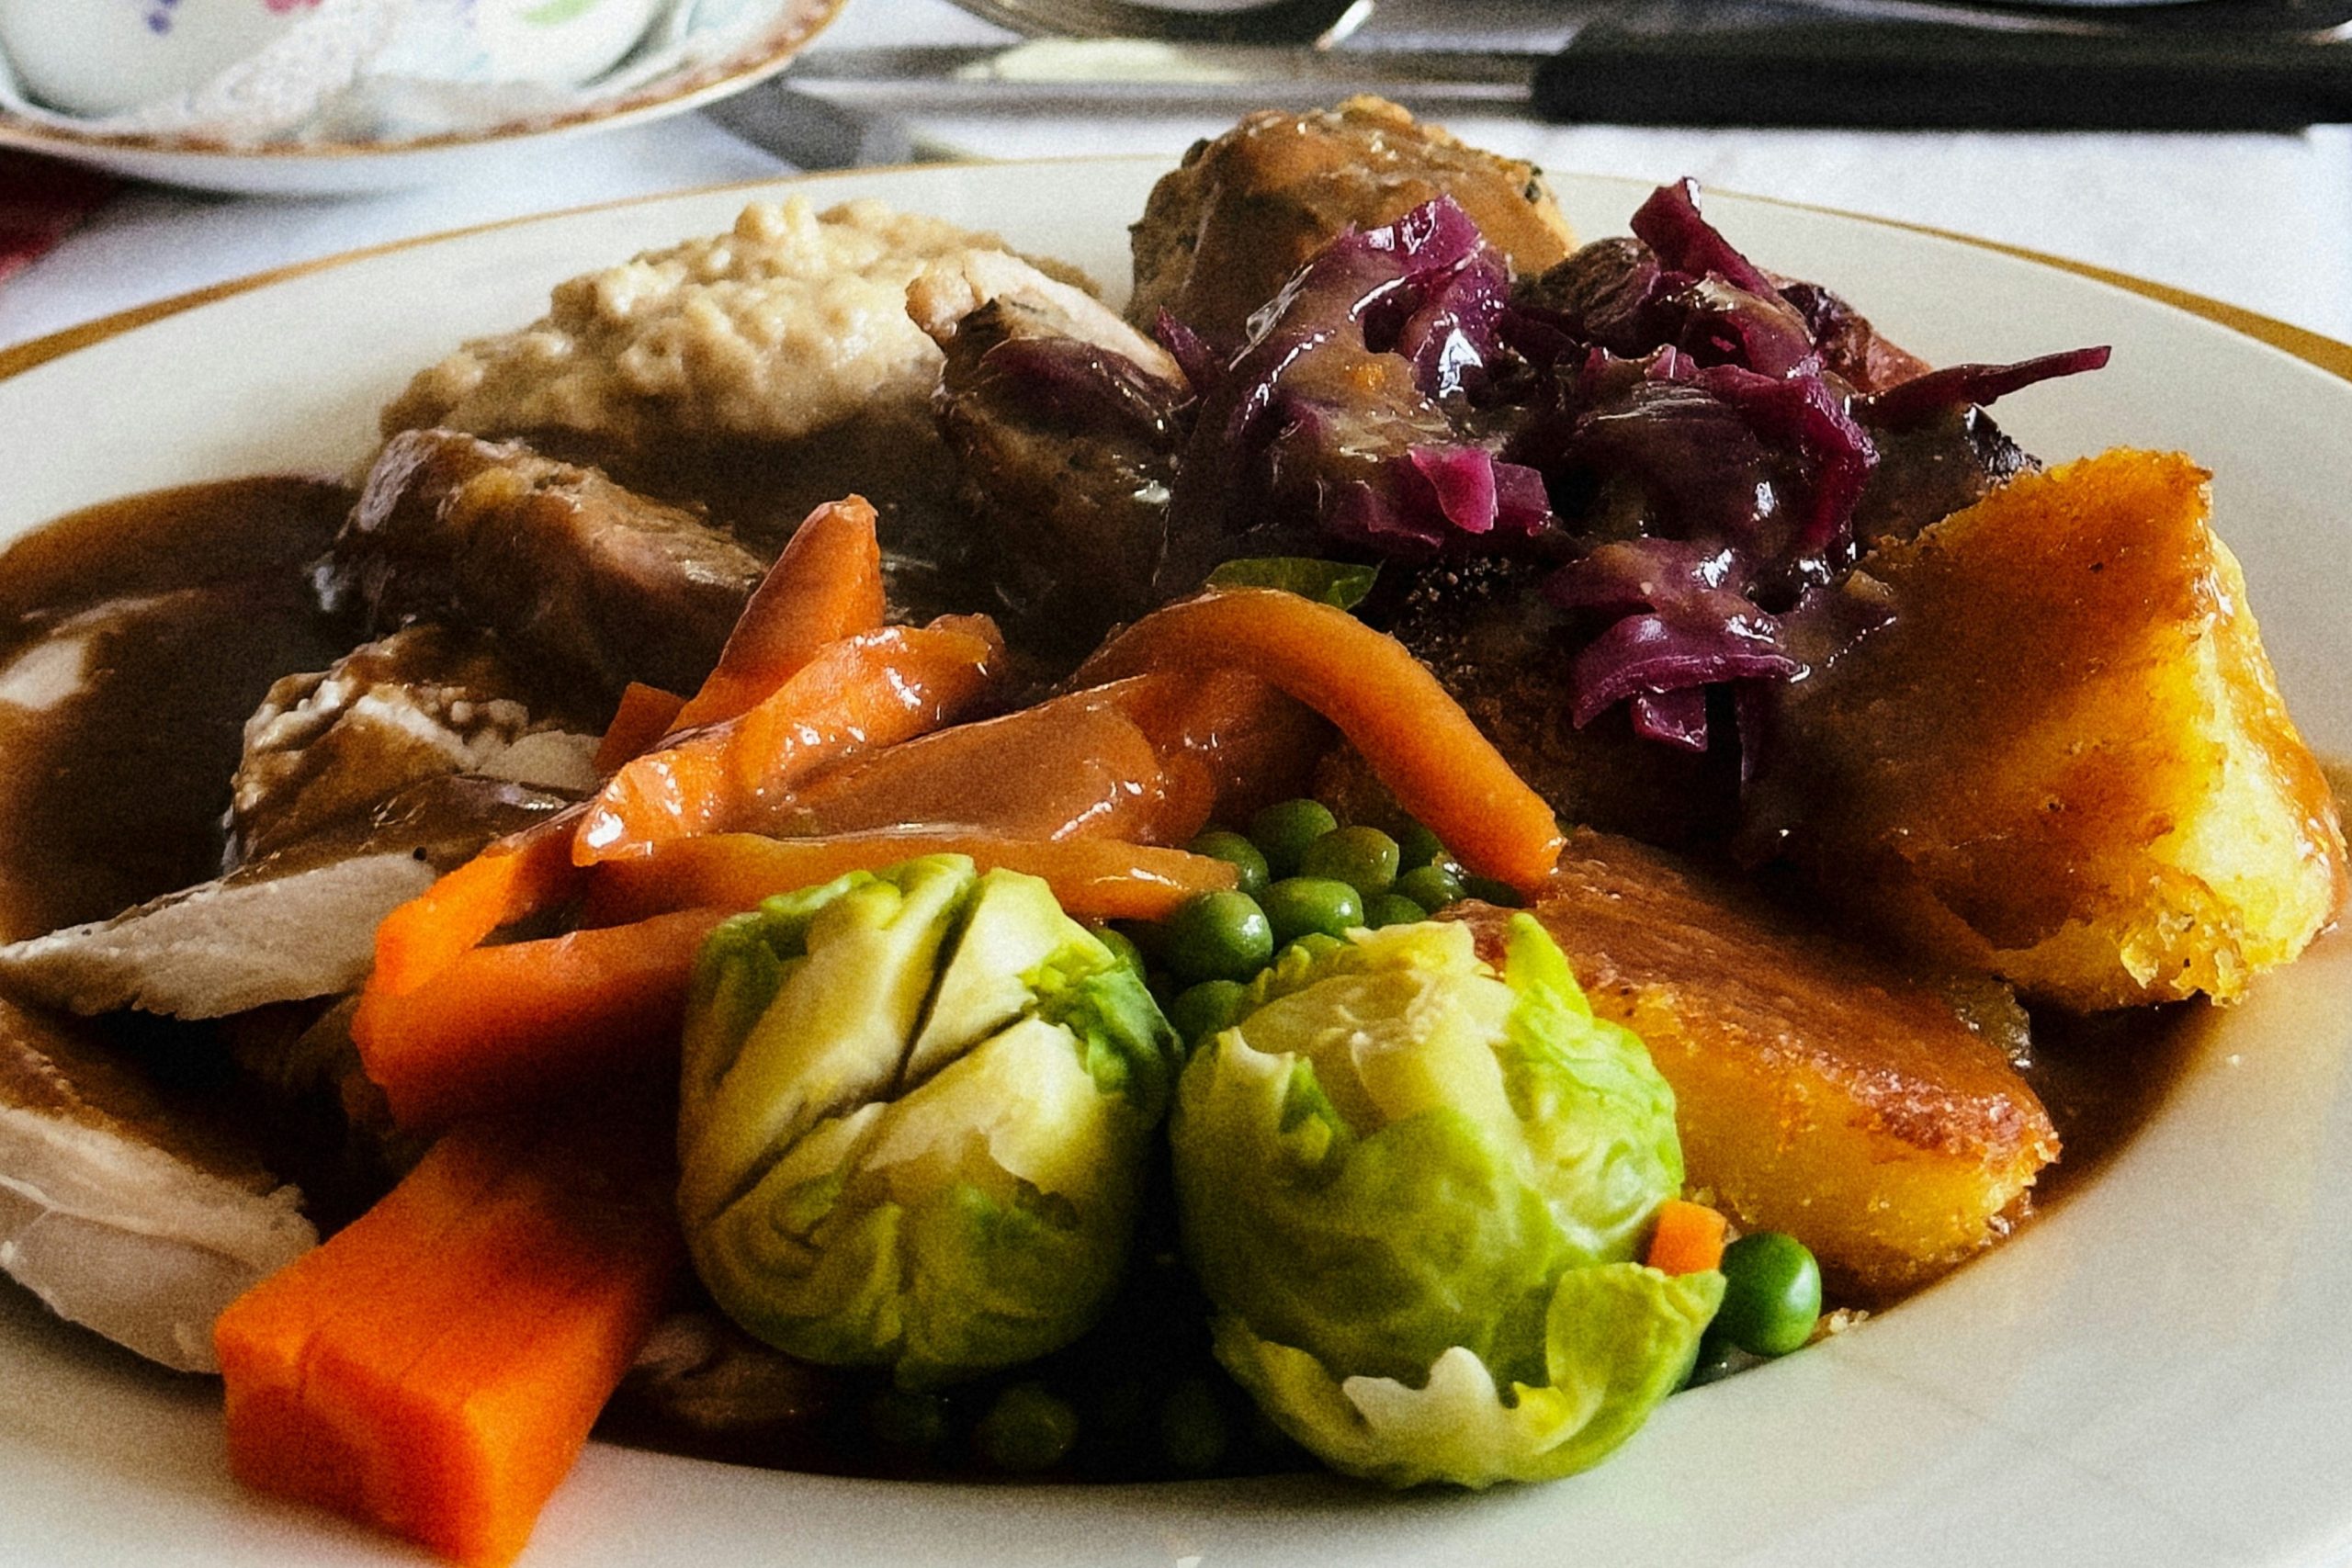
As the weather cooled, the number of shoppers buying hot chocolate rose by 41% in September when compared with August, while those buying soup increased by 35%. Hearty home cooking made a comeback too, with 24% more shoppers buying gravy and 35% more buying frozen roast potatoes.
Chocolate prices fall
Looking to Halloween, 1.2 million households bought a pumpkin over the latest four weeks, which was an increase of 10% compared with the same time last year. Like-for-like prices on chocolate confectionary fell by 3% during the same period.
McKevitt added: “Halloween and Christmas are two of the most important moments of the year for chocolate confectionery, so falling prices will be welcome news for shoppers and retailers alike. After the double digit increases of 2025, a 3% drop won’t fully reverse what consumers have paid in recent months, but it should help ease some of the pressure on household budgets as the festive season approaches.”
Over the 12 weeks to 4th October, Lidl led in market share gains, climbing to 8.6%, up from 8.2% at the same time last year. Sales at Lidl were 7.1% higher, with strong growth across categories such as fruit, vegetables and wine. The discounter welcomed more than half a million additional customers through the doors over the 12-week period.
Sales at online specialist Ocado increased by 12.4%, outpacing overall online sales at 5.5%. Ocado accounted for 2.2% of the market, up from 2% a year ago.
Morrisons maintained the same 8.3% share of the market as in 2025, with sales up by 1.8%. Spending through the tills was 1% higher at Tesco and 1.3% higher at Sainsbury’s with the two retailers holding 27.8% and 15.2% of the market, respectively. Asda share now stands at 11.5%, while Aldi holds 10.5% of the market, with sales at the discounter up 0.4% year-on-year.
Waitrose sales increased by 2.3% with market share unchanged at 4.4%. Market share for Co-op also held steady capturing 5.4% of take-home spending at the grocers as sales rose by 1.8%. Iceland sales were up by 0.2%, with share now at 2.2% of the market. Grocery sales at M&S rose by 14.9%.